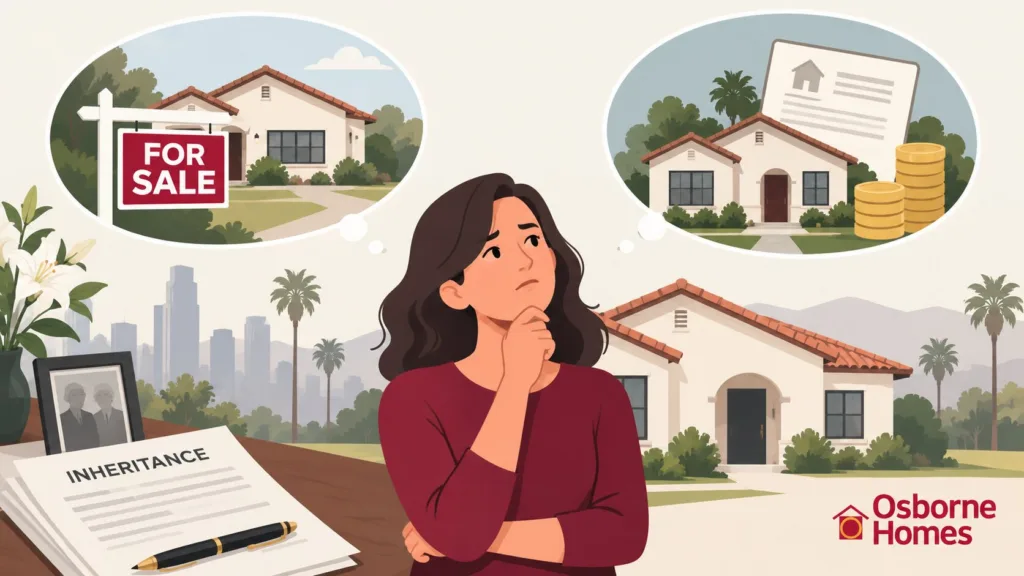
If you are inheriting a house in California, selling or keeping it usually turns on holding costs, capital-gains tax and whether the co-heirs agree. Inherited property generally gets a stepped-up cost basis equal to its date-of-death value, so a sale soon after the death often produces little or no taxable gain. Either way, someone needs legal authority to sell before the house can change hands.
lightbulbKey Takeaways
check_circle
Most sell-or-keep decisions come down to what the house costs each month and whether the co-heirs agree.
check_circle
Inherited property generally takes a stepped-up basis equal to its fair market value on the date of death, which often limits capital-gains tax on a prompt sale.
check_circle
For deaths in 2026 the federal estate tax applies only above a $15,000,000 exclusion per person, and California has no estate tax return requirement for deaths since 2005.
check_circle
A house usually needs court-granted authority to sell, unless it sits in a living trust or qualifies for the AB 2016 simplified procedure, which covers a primary residence worth $750,000 or less when the owner died on or after April 1, 2025.
check_circle
Keeping the house means paying the mortgage, property tax, insurance and upkeep from the start, and the county may reassess the property at market value unless the Prop 19 exclusion applies.
check_circle
Selling as-is to a cash buyer means no repairs before closing, though the sale still waits until someone has authority to sell.
Inheriting a house in California usually arrives with a mortgage balance, a property tax bill and a repair list nobody budgeted for. The person handling it may be grieving, living out of state, or both. Those bills start before anyone has decided what to do with the house.
Before we begin: The tax and legal points here are general information, not advice for your situation. A California CPA can confirm the tax details, and a probate attorney can tell you who has the authority to sign a sale.
Start with two numbers, what the house would cost you each month and what it would sell for as it stands.
Then weigh them against what you want from the home.
Give yourself time to grieve before you decide anything. The house may hold years of family memories, and that counts, but the monthly costs and the sale price do not change with how you feel about it.
Gathering the facts first, starting with the numbers below, makes either choice easier to explain to the rest of the family later.
Keeping the property can preserve family connections, and it lets you hold the home through any future appreciation. It fits best when someone plans to live there and the costs are covered without strain.
Renting can generate monthly income while keeping the property in the family. However, landlord duties come with that income, including repairs, tenant screening and an insurance policy written for a rental, and rental income and expenses have their own tax rules to run past a CPA.
Selling provides immediate funds, ends ongoing maintenance costs and any mortgage payments, and simplifies settling the estate. It is also the practical answer when co-heirs want different things or the house needs more work than anyone will fund.
Distance counts too, because a house in Fresno is hard to manage from, let’s say, Seattle or out of state.
A traditional market sale means engaging a real estate agent, investing in repairs, preparing for marketing and showings, negotiating with buyers, and expecting a potentially lengthy process. The alternative is a direct sale to a buyer who pays cash and takes the house as it stands.
Osborne Homes is a California real estate investment company, in business since 2007, that buys houses directly for cash, as-is, as an investor and not as an agent, so the seller makes no repairs and pays no agent commission. Our page on how to sell an inherited house in California covers that route in more detail.
The tax question comes down to one number, the house’s value on the date of death.
Under federal tax rules, the basis of inherited property is generally its fair market value on the date of the owner’s death, or its value on an alternate valuation date if the estate chooses one. Your capital gain is the sale price minus that basis, so what the owner paid decades ago mostly stops mattering.
Here’s a quick, made-up example: A parent bought a house for $180,000, it was worth $750,000 at death, and you sell it for $765,000. Your taxable gain is $15,000, not $585,000.
California does not impose inheritance tax. The state’s estate tax was phased out, and the State Controller says deaths on or after January 1, 2005 need no California estate tax return. An inheritance is also not taxable income in California, although the gain on a real property sale is. The federal estate tax reaches only very large estates, since the basic exclusion is $15,000,000 for 2026 deaths.
Keep in mind that basis rules have a few exceptions, so have a CPA confirm the number before you file.
Before you can sell your inherited California property, someone has to hold legal authority to sign for it.
A house titled in the owner’s name alone generally needs a court-appointed executor or administrator first, and the letters the court issues say whether that person has full or limited authority. Probate itself covers court filings, creditor and beneficiary notices, an inventory and appraisal, and court approval before assets are distributed. With full authority, the representative can sell real property after mailing a Notice of Proposed Action at least 15 days ahead and hearing no objection. With limited authority, the sale needs a court hearing and approval.
Closing the whole estate takes longer than selling the house. The inventory and appraisal is due within four months of the appointment, and creditors generally have at least four months after the letters issue to file claims, so a sale can happen while the estate stays open.
If the house is held in a trust, the process differs from probate, and the trustee rather than a court usually controls the transfer. Confirm on the recorded deed that the trust actually holds title before assuming this route applies, and see our guide to inheriting a house in a trust for the trustee’s steps.
A third route is newer. Under AB 2016, a successor can petition the court for an order determining succession to the decedent’s primary residence when its gross value is $750,000 or less.
It applies to deaths on or after April 1, 2025, a probate referee sets the value, and the petition, Judicial Council form DE-310, cannot be filed until 40 days after the death. The successor must notify each heir and devisee within five business days of filing, and the order, once recorded with the county, puts title in the successor’s name. A rental or commercial property does not qualify, and earlier deaths fall under lower limits.
Our guide on whether you can sell before probate is granted goes deeper on the court steps, and clearing out the contents is a separate job covered in our guide to removing items after death. A probate attorney can confirm which route fits your estate before you list the house or accept an offer.
Keeping an inherited home means paying for it every month, and the property tax line can jump if the county reassesses the house.
Inherited properties can come with financial responsibilities such as existing mortgages, unpaid property taxes, maintenance costs, and insurance requirements. Be aware of hidden costs, including emergency repairs, property management fees, and legal expenses.
California’s basic property tax rate is 1% of assessed value, plus charges for voter-approved debt, and a change in ownership resets the assessed value to current market value. A transfer to an heir can count as a change in ownership, so a home a parent held for decades may be taxed on a much higher base once it is yours.
Proposition 19 gives some heirs a way out. A child can keep the parent’s lower assessed value, up to a limit, if the home was the parent’s principal residence and becomes the child’s principal residence.
The homeowners’ exemption claim has to be filed within one year of the death, and the reassessment exclusion itself is claimed on form BOE-19-P within three years of the death or before the home is transferred to someone else, whichever comes first.
If the home’s market value exceeds the parent’s taxable value by more than $1,044,586, the excess is added to the new taxable value. That figure applies to transfers from February 16, 2025 through February 15, 2027. Rentals do not qualify.
Insurance needs attention early. A home is generally considered vacant after 30 to 60 days, and a standard homeowners policy may stop covering it at that point, so ask the insurer what applies once the house is empty.
Use the decision tree to see which way your own situation leans, then fill in the cost worksheet to test the numbers.
| Step | Question | If yes | If no |
| 1 | Can you cover the mortgage, property tax, insurance and upkeep without strain? | Go to step 2 | Selling usually fits |
| 2 | Do all the co-heirs agree to keep the house? | Go to step 3 | Selling usually fits, or one heir buys out the others |
| 3 | Is the house livable as it stands, or can you pay for the repairs it needs? | Go to step 4 | Selling as-is usually fits |
| 4 | Will someone live in the house or rent it out? | Keeping usually fits | Selling usually fits |
A single no usually points toward selling.
| Cost | Where the number comes from | Watch for |
| Mortgage payment | Latest loan statement from the servicer | Payments keep falling due while the estate is settled |
| Property tax | Current bill, then 1% of the new assessed value plus local charges after any reassessment | Prop 19 can keep the old base if the claim is filed in time |
| Insurance | Quote from the current insurer for a home that may sit empty | Coverage limits once the house counts as vacant |
| Maintenance and utilities | Last 12 months of bills, plus a contractor quote for known repairs | Emergency repairs on a house nobody is checking |
| Lost rent | Months to find a tenant times local market rent | Only applies if you plan to rent |
As an example with made-up numbers, a house reassessed at $700,000 would carry a base property tax of about $7,000 a year, or roughly $583 a month, before voter-approved charges.
Sell if you cannot comfortably carry the costs, if the co-heirs disagree, or if the house needs repairs nobody will fund. Keep it if someone plans to live there or rent it and the numbers work. The decision tree above takes those questions in order.
You pay tax only on gain above the stepped-up basis, which is generally the home’s value on the date of death. If you sell close to that value, the taxable gain is often small or zero. California counts any gain as income.
Yes, once the court has appointed an executor or administrator with authority to sell. The house does not have to wait for the whole estate to close, which takes longer because creditors get at least four months to file claims. With limited authority, the sale also needs court approval at a hearing.
No. California has no inheritance tax, and an inherited house is not taxed as income when you receive it. Federal estate tax applies only above $15,000,000 per person for 2026 deaths. Income the house produces later, such as rent or gain on a sale, is taxable.
The county can reassess an inherited home at current market value, which often raises the bill. Under Prop 19, a child who makes the house their primary residence can keep the parent’s lower assessed value, up to the old value plus $1,044,586 for transfers through February 15, 2027. The homeowners’ exemption claim is due within one year of the death.
Start with a conversation about who wants what, because heirs who agree can sell on their own timeline. Consider buyout arrangements, agree on property disposition, seek professional mediation if necessary, and ensure fair distribution of proceeds from a sale. If talks stall, a co-owner can ask a California court for a partition, and our guide to forcing a sale of a jointly owned property shows the steps.
Before you decide, fill in the cost worksheet above, including the property tax a reassessment could add. If speed and a firm closing date matter more than the highest possible price, a direct cash sale is worth comparing with a traditional listing.
Osborne Homes makes a no-obligation cash offer and can close in as few as 7 days once authority to sell is in place, and you can get in touch with us online to ask about your situation and get your cash offer.
This article is general information, not legal, tax or financial advice. Every estate is different, so talk to a California CPA and a probate attorney before you act.

The Osborne Homes Team
The Osborne Homes team specializes in California real estate, helping buyers, sellers, and homeowners navigate the market with clarity and confidence. Our articles are written to provide practical guidance, local insight, and up-to-date information you can trust.
Get a no-obligation cash offer in as little as 48 hours. No repairs, no agents, no stress. Just a dignified way to move forward.
Free property assessment. No obligation. No pressure.
sell